

Bank of America Mobile Banking
by Bank of America
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
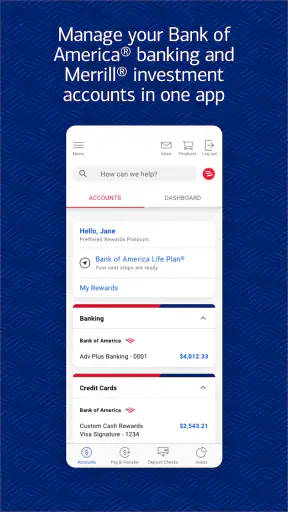
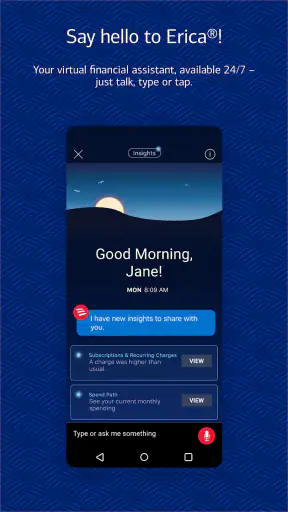
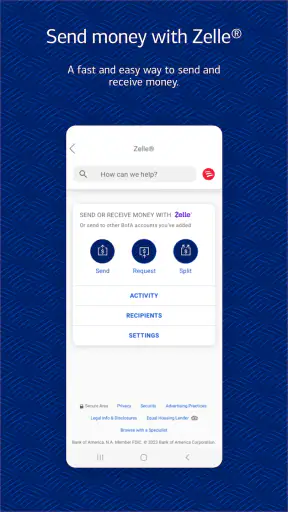
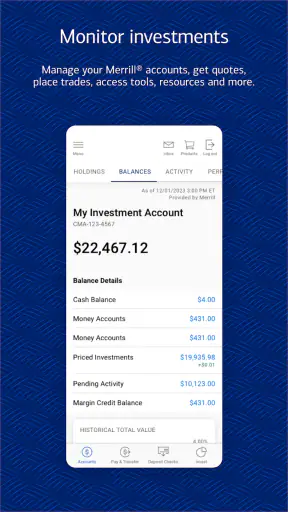
 Analysis by Getfullapps
Bank of America Mobile Banking is the kind of finance app I would suggest to someone who wants to handle everyday banking without turning every small task into a visit to a branch. I used it with a first-time user in mind, paying attention to the path from installation to a genuinely useful result: getting oriented, checking an account, and completing a normal banking task with as little uncertainty as possible. It is a free app from Bank of America for Android and iOS, aimed at everyone rather than a specialist financial audience.
That broad audience is important. The app is not presented as a separate budgeting tool or an investing platform alone; it brings banking, budgeting, and investing into one place. In practice, that makes it most useful when your financial life already touches Bank of America. If your checking, savings, cards, or other services are elsewhere, the experience becomes less central to your routine. I would not install it simply because it is popular. I would install it because I want a direct mobile doorway into Bank of America accounts.
What to expect before you begin
The first thing I noticed is that this is a full banking workspace rather than a lightweight balance checker. You can expect the app to put everyday account information and money-management tools close together, so the home experience can feel more substantial than a simple list of recent transactions. That is helpful once you know where you are going, but a new user may need a little time to understand which area is best for a particular task.
Its scale gives some reassurance. The app has passed 50 million installs and holds a 4.6 average from around 1.2 million ratings. Those figures do not guarantee that every person will find it effortless, but they suggest that Bank of America has built a mobile service intended for regular, high-volume use rather than a temporary companion app.
I also like that the age classification is Everyone. That does not remove the need for sensible security habits, especially on a shared phone, but it signals that the interface is meant for ordinary account holders rather than financial professionals. The developer is Bank of America, which matters here because the app’s usefulness depends on its connection to that institution, not merely on the quality of its screens.
The current version is 26.07.02, and the minimum operating-system requirement is 11. Before installing, I would check the software version on an older phone. This is a small step, but it prevents a frustrating situation in which someone expects to begin immediately and discovers that the device needs an update first.
Once installed, I would avoid trying to explore every section at once. A better first visit is deliberately narrow: sign in, identify the main account, inspect the latest activity, and decide what one task matters most today. That approach makes the app feel less like a large financial dashboard and more like a useful tool.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Who will get the most from it
I think it is a strong fit for Bank of America customers who want one mobile place for routine money decisions. A person checking whether a paycheck arrived, reviewing a card purchase, moving through a budgeting view, or looking at investment information can benefit from having these activities connected to the same banking relationship. The convenience comes from continuity: you are not starting from a blank third-party finance app every time.
It is also a sensible choice for someone who values access while away from a computer. A laptop may still be more comfortable for careful financial planning, but a phone is often nearby when a decision needs to be made. The app is especially practical for quick checks before a purchase, after a bill payment, or when reviewing whether recent activity matches your expectations.
I would be more cautious if you are looking for a bank-independent budgeting service. A dedicated budgeting app may be better when your main goal is to combine accounts from several institutions, compare spending across a complicated household, or build a highly customized long-term financial system. Bank of America Mobile Banking is strongest when Bank of America is the center of the picture.
Getting through the first setup
After installation, I would treat sign-in as the main setup rather than rushing into customization. Use the account credentials and verification steps associated with your Bank of America relationship, then pause once the account overview appears. The important first milestone is not changing every preference; it is confirming that you are looking at the correct financial relationship and that the information is presented in a way you recognize.
This is where a first-time user should be patient. Banking apps are not the right place for guesswork with usernames, passwords, or verification prompts. If a screen asks you to confirm something, read it carefully instead of tapping through automatically. I also recommend setting up the phone’s own lock and keeping the app away from a shared device profile. Those habits are more valuable than any visual customization.
The first useful setup check is to locate your primary checking or savings account and open its recent activity. Look for a familiar transaction rather than trying to memorize the entire screen. A recent purchase or deposit gives you a practical anchor and helps you understand how the app labels dates, amounts, and account activity.
One detail that can save time is deciding what you want to see first on future visits. If your normal routine is checking available money before leaving home, make that the first destination you learn. If you mainly review card activity, focus on the path to transactions. The app becomes easier when you build a personal route instead of trying to learn its whole structure in one sitting.
I would also resist treating the budgeting and investing areas as mandatory setup steps. They are useful parts of the broader service, but they do not need to distract from the basic banking task that brought you there. First establish confidence with account viewing; then explore additional tools when you have a clear question they can help answer.
The first successful action I recommend
For a new user, my preferred first success is a simple account-activity review. Open the main account, inspect the latest entries, and compare one or two of them with receipts, alerts, or your own memory. This is low-pressure, immediately useful, and teaches you more about the app than tapping through promotional panels or browsing every menu.
A realistic example is checking your balance before buying groceries after a busy week. I would open the app, confirm the account I intend to use, review the latest deposit and recent card or debit activity, and then make my decision with current information rather than relying on an old mental estimate. The value is not dramatic; it is the small reduction in uncertainty that makes mobile banking worthwhile.
Another good first action is reviewing a recent payment or transfer that you already expected to see. The point is to learn how completed activity appears, not to experiment with an unfamiliar financial action. Once you understand the difference between viewing an entry and initiating something, you are in a much safer position to use the more active parts of the app.
This is also where I would create a repeatable routine. For example, after a weekly payday, spend a few minutes checking the main account, scanning recent activity, and looking at the budgeting view if you use it. That workflow is more useful than opening the app only during a moment of panic. It turns the phone into a regular checkpoint rather than an emergency calculator.
When you are ready to do more, choose one action with a clear purpose. You might review spending to understand why the balance changed, examine an investing section because you already manage investments with Bank of America, or use the account information to prepare for an upcoming payment. The best next action is the one that answers a real question you have today.
Where new users can become confused
The biggest possible confusion is assuming that every area has the same purpose. Banking, budgeting, and investing may appear within the same overall experience, but they answer different questions. Banking helps you understand current account activity, budgeting helps you interpret patterns, and investing is connected to a longer-term view. If you open the app without deciding which question you are asking, the range of choices can feel larger than necessary.
I would also avoid reading a displayed balance as a complete picture of what you can comfortably spend. Account information is useful, but real-life decisions may involve pending activity, upcoming bills, or money you have mentally reserved for another purpose. My habit is to review recent transactions and upcoming commitments before making a larger decision, rather than treating one number as a personal spending limit.
Another point of friction is the difference between reviewing information and taking action. A screen that shows an account or transaction is not the same as a screen that changes where money goes. For a first-time user, I recommend slowing down whenever a task moves from observation to confirmation. Read the amount, destination, and timing shown on the final review screen before proceeding.
People can also become distracted by the app’s breadth. Because it includes more than basic checking, it may invite you to explore budgeting or investing before you have finished the simple task you came to do. I see that as a design trade-off rather than a fatal flaw: the connected tools are convenient, but the wider scope means the user has to supply some discipline.
There is a similar trade-off when comparing it with a bank’s website. A desktop browser can provide more room for side-by-side review and careful planning, while the mobile app is better suited to quick checks and short sessions. I would use the phone for immediate awareness and the website when I want to study several pieces of financial information at once.
Compared with a standalone budgeting app, Bank of America Mobile Banking has a different center of gravity. A separate budgeting service may be preferable for a household that wants a neutral view across multiple banks. This app makes more sense when direct access to Bank of America accounts is the priority and budgeting is part of that same relationship rather than the entire mission.
Compared with visiting a branch, the app is obviously more convenient for routine information. Still, digital convenience does not make every financial situation simple. If you are dealing with an unusual account issue or need careful human guidance, I would not force the problem through a phone screen just because the app is available. The right tool depends on whether the task is routine or exceptional.
Three habits that make the experience better
First, use a “verify, then act” rhythm. I check the account identity and recent activity before beginning anything that changes money movement. This takes only a moment and is especially helpful when several accounts appear similar. It is a simple safeguard that generic app advice often overlooks.
Second, separate review days from exploration days. When I need to know whether a transaction posted, I do not start browsing investing information. When I want to understand spending, I give the budgeting area my attention instead of mixing the task with unrelated account actions. This keeps short visits focused and reduces the chance of confirming something without fully reading it.
Third, use a small recurring check rather than waiting for a problem. A quick look after expected income or before a major weekly purchase can reveal activity that deserves attention while it is still easy to remember. The app is most valuable when it supports that calm routine, not only when a balance looks surprising.
A fourth useful habit is to keep the app’s role clear in a shared household. If more than one person handles finances, agree on which account or activity needs review and avoid making changes casually from someone else’s device session. The app may be designed for everyday access, but financial actions still deserve individual attention and a clear handoff.
What to do after the first visit
Once the basic account review feels familiar, I would move to the feature that matches your actual routine. If you often wonder where money went, explore the budgeting side with a specific spending question. If you already have a Bank of America investing relationship, review that area when you have enough time to think rather than treating it like a quick balance glance. The app rewards purposeful exploration more than random tapping.
It is worth deciding what “success” means for you. For one person, it is knowing the current account position before paying a bill. For another, it is spotting an unfamiliar transaction quickly. Someone else may care about bringing banking and investing into the same mobile routine. Defining that outcome keeps the app from becoming another screen you open without learning anything.
I would also keep expectations realistic about mobile finance. The app can make access easier, but it cannot replace good decisions about spending, saving, or investing. Its strongest contribution is visibility and convenience. You still need to interpret the information, check details, and choose whether an action fits your circumstances.
Bank of America Mobile Banking is free, which removes the usual barrier to trying it when you already bank with the developer. Its Everyone age rating and broad feature set make it approachable, while the large installed base and around 440 thousand written reviews show that it is a heavily used service. I would treat those signs as context, not as a reason to ignore your own preferences or device limitations.
My final recommendation is straightforward: if Bank of America is your primary financial institution, I think this app is worth installing and learning through one small, controlled task at a time. Start by confirming your account, review familiar activity, and only then expand into budgeting or investing. If you need a multi-bank command center or a deeply specialized planning tool, a different app may suit you better. For everyday Bank of America access on a phone, though, Bank of America Mobile Banking offers a practical balance of reach, convenience, and financial context, provided you use its broader menu with a little intention.
Pros
- User-friendly interface enhances navigation.
- Quick access to account balances and activity.
- Secure login with fingerprint and Face ID.
- Seamless money transfer and bill pay options.
- Real-time alerts for transactions and updates.
Cons
- Limited functionality for certain account types.
- Occasional app crashes during peak hours.
- Some features require a stable internet connection.
- Mobile deposit limits can be restrictive.
- Updates may temporarily disrupt app performance.
FAQs for Bank of America Mobile Banking
Is the Bank of America Mobile Banking app secure?
Yes, the Bank of America Mobile Banking app is highly secure. It uses advanced encryption and multiple layers of security to protect your personal and financial information. Additionally, you can enable biometric logins like fingerprint or facial recognition to enhance security, ensuring that only you can access your account.
What features does the Bank of America Mobile Banking app offer?
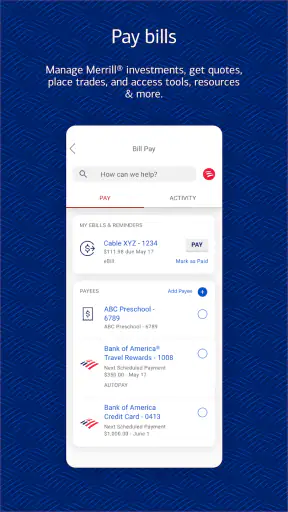
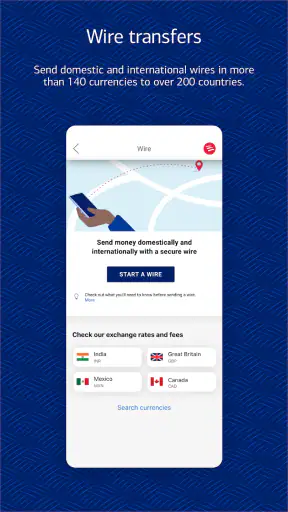
The app offers a wide range of features, including mobile check deposit, bill pay, money transfers, and account alerts. You can also view account balances, transaction history, and set up customized alerts. Additionally, the app provides access to financial management tools to help you monitor your spending and budgets.
Can I deposit checks using the Bank of America Mobile Banking app?
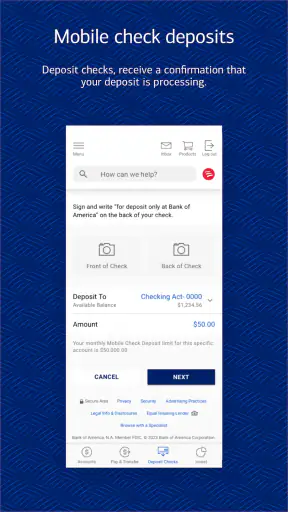
Yes, you can deposit checks directly through the app using the mobile check deposit feature. Simply take a photo of the front and back of the check with your smartphone, and follow the on-screen instructions. This feature saves you time by eliminating the need to visit a bank branch.
Is the Bank of America Mobile Banking app free to use?
The app itself is free to download and use. However, standard messaging and data rates from your mobile carrier may apply. Additionally, certain transactions or services might incur fees according to your account terms, so it's advisable to check with Bank of America for any specific charges related to your banking activities.
Can I use the app internationally?
Yes, the Bank of America Mobile Banking app can be used internationally, provided you have internet access. However, be aware of potential international data roaming charges from your mobile carrier. It's recommended to connect to Wi-Fi when available to avoid these charges while using the app abroad.

Bank of America Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobileappstore@bofa.com, visit https://www.bankofamerica.com/mobile/mobile-banking-help.go, or review their https://www.bankofamerica.com/privacy/overview.go.










